
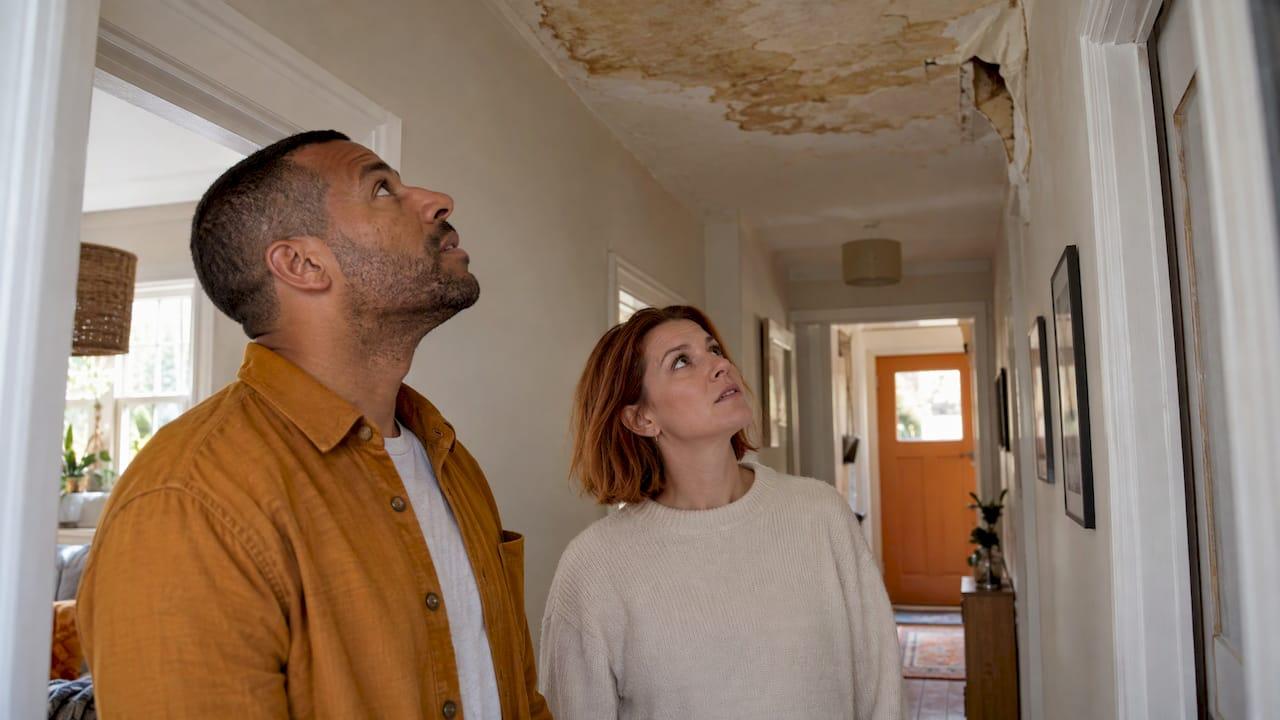
Yes, you can sell a house while an insurance claim is still open. Nothing in the law of the states we work in stops you. What matters is what your purchase contract says about the claim, because selling the property does not automatically move the claim to the buyer. If the contract says nothing, the claim generally stays with you. Your lender, your buyer and your policy language all shape how much of the money you actually keep.
Below is how an open claim interacts with a sale, who gets paid, what you must disclose, and what your realistic options are if you do not want to repair the house first.
TL;DR
- You can sell with an open claim. The claim is a contract between you and your insurer, separate from the deed to the house.
- Who collects the payout depends on the sale contract and any assignment of benefits. Silence in the contract usually leaves the claim with the seller.
- Your mortgage servicer is often a payee on the check, so a payoff and the claim money have to be sorted out together.
- Known damage and a pending claim generally belong on your disclosure form. Rules differ by state.
- An as-is cash sale lets you skip repairs and set the claim terms in writing before closing.
Table of Contents
- What an open claim means for a sale
- Who gets the insurance money after you sell
- Your mortgage lender and the claim check
- What you must disclose to a buyer
- Is the insurance payout taxable?
- Your options with an open claim
- A checklist before you sign anything
- Perspective
- Sell your damaged house as-is for cash
- FAQ
- Sources
What an open claim means for a sale
An open claim means you reported a loss, such as fire, water, wind or hail, and the insurer has not finished paying or closing the file. The house may still be damaged, partly repaired, or fully repaired with a final payment pending.
A sale conveys title to the real estate. The insurance claim is a separate contractual right. A Florida law firm describes it as a right that belongs to the policyholder at the time of the loss, separate from title to the property. United Policyholders, a nonprofit consumer group, says a claim will not typically be terminated just because you sell after a loss and before repairs, though where and how the money is paid depends on the contracts and your circumstances.
That sounds simple, but three groups care about the claim: you, your lender and the buyer. Each has a different interest.
Who gets the insurance money after you sell
There are three common outcomes, and the purchase agreement decides which one applies.
You keep the claim. The contract reserves the claim proceeds for you, and the buyer takes the house in its current condition. The price usually reflects the unrepaired damage. This is the cleanest setup when the buyer is paying cash and does not want to deal with your insurer.
You assign the claim to the buyer. The buyer steps into your position, collects the proceeds and handles repairs. Policies and state laws can limit this. United Policyholders notes that many states allow assignment of policy benefits when it happens after the loss, but policy language may restrict it. Florida is a good example of how much rules can differ: a 2024 bill there would void assignments of post-loss benefits under property policies issued on or after January 1, 2023, with exceptions that include a transfer to a subsequent purchaser with an insurable interest. Ask an attorney in your state before you rely on an assignment.
The claim is settled before closing. You accept the insurer's payment, close the file, and sell the house as it stands. This removes loose ends, but you give up any later supplement for damage the first estimate missed.

Actual cash value versus replacement cost
The type of coverage changes what you can collect if you sell before repairs. With replacement-cost coverage, the insurer typically pays actual cash value first, which is repair or replacement cost minus depreciation. The withheld depreciation is recoverable once the item is repaired or replaced, according to one insurer's claims guide.
So what happens to that holdback when you sell the damaged house? United Policyholders says a seller who retains the benefits and sells in the damaged state is "more than likely" entitled to actual cash value whether or not the seller rebuilds, while recovering the holdback depends on other factors. One federal appeals court case is worth knowing about. In Edgewood Manor Apartment Homes v. RSUI Indemnity, the Seventh Circuit held that selling the property unrepaired did not extinguish the seller's right to replacement-cost proceeds, because the policy did not require the insured to do the repairs personally. That was one policy and one court, so read your own policy's repair and suit-limitation wording, and ask the insurer in writing how a sale affects your claim.
Your mortgage lender and the claim check
If you have a mortgage, the claim money rarely goes straight to you. The Consumer Financial Protection Bureau explains that the insurer generally issues the check to you and your mortgage servicer or lender together, and that the servicer typically releases some funds before work starts, more as work progresses, and the rest after the home passes inspection.
For loans backed by Fannie Mae, the servicing guide lets the servicer make an initial release if the loan was current or less than 31 days delinquent at the time of the loss. That release can be up to the greater of $40,000, 33% of the loss proceeds, or a calculated excess over the balance. The rest is released in stages.
What this means for a sale:
- Ask the servicer what it holds. Find out whether any loss draft money is sitting in a restricted account and what it takes to release it at payoff.
- Expect the payoff to come first. Courts have enforced mortgage language that assigns insurance proceeds to the lender up to the unpaid debt. In R.I. Joint Reinsurance Ass'n v. Rosario, the Rhode Island Supreme Court held that the servicer was entitled to the entire proceeds under that mortgage's wording.
- Put the loan payoff and the claim in the same conversation. The title company or closing attorney should know about the open claim before the closing statement is drafted.
If you are behind on payments as well, speed matters more. Our Cash Offer Program is built for owners who are facing foreclosure and need a clear timeline.
What you must disclose to a buyer
Damage you know about and a claim tied to it generally belong on your disclosure paperwork. Disclosure law varies, so here are two examples from states where we buy.
New Jersey. The state's Division of Consumer Affairs instructions say sellers must answer the disclosure questions before the purchaser becomes obligated under a contract, and that the seller must also disclose known material defects even when the printed form does not ask about them.
Texas. Section 5.008 of the Property Code requires a written Seller's Disclosure Notice for residential property of no more than one dwelling unit, delivered on or before the effective date of the contract. If you hand it over after the contract is signed, the buyer may terminate within seven days of receiving it.
Across states, the practical rule is the same: describe what was damaged, say that a claim was filed, and state what has and has not been repaired. Being precise helps you. A structural inspection write-up, like this structural defects inspection guide, shows how professionals separate cosmetic wear from structural problems, which is the kind of distinction a good disclosure makes. Our own guide to as-is disclosure laws covers how selling as-is interacts with these duties.
Selling as-is does not mean hiding anything. It means you are not promising to fix the house, and the buyer accepts it in its current condition after you have been honest about that condition.

Is the insurance payout taxable?
A homeowners payout is generally treated as reimbursement for a loss, not income. MoneyGeek notes that tax consequences can arise if the payout exceeds the property's adjusted basis. The IRS covers how casualty losses and insurance reimbursements are handled in Publication 547. A sale on top of a claim can affect your gain or loss calculation, so ask a CPA or enrolled agent to run the numbers before closing, especially with a large payout.
Your options with an open claim
| Option | Repairs needed | Who handles the claim | Best when |
|---|---|---|---|
| Repair, finish the claim, then list | Yes, all of them | You | You have time, cash flow and energy for a contractor |
| List as-is with an agent | No | Depends on contract | The house is still financeable by a typical buyer |
| Assign the claim to the buyer | No | Buyer, if allowed | Your policy and state permit it and the buyer wants it |
| Sell as-is for cash, keep the claim | No | You, per the contract | You want out and want the payout kept separate |
Damaged houses often fail the buyer's lender inspection or appraisal, and an unrepaired roof, water intrusion or fire damage can stall a conventional sale. If that is your situation, these guides go deeper by damage type: selling a fire-damaged house, selling a water-damaged house, selling a flood-damaged house and selling a hurricane-damaged house. For the general case, read selling a home without repairs.
A checklist before you sign anything
- Read your policy sections on loss payment, repairs and any time limit for suing or finishing the claim.
- Call your insurer and ask, in writing, how a sale affects your open claim and any holdback.
- Get your mortgage servicer's payoff figure and the balance of any loss draft funds.
- Save the adjuster's estimate, photos, receipts and correspondence. They support both your disclosure and your price.
- Have the contract state who owns the claim, who handles supplements, and what happens to proceeds that arrive after closing.
- Bring in a real estate attorney in your state if you are considering assigning the claim.
- Keep the claim file open and the insurer informed through closing, so you do not miss a deadline.
Perspective
Most owners who call us about an open claim are worried about one thing: will selling cost them the money the insurer owes them? In our experience the answer comes down to paperwork, not to the sale itself. When the contract says plainly who keeps the claim, the sale and the claim can run side by side.
That is why we look at the claim as part of the offer, not as an obstacle. We buy houses as-is, so you do not need to wait for contractors, re-inspections or a buyer's financing to fall through. We do not charge commissions or agent fees, and we explain our cash offer in numbers so you can see what you would net.
Damaged houses, liens, tenants and foreclosure deadlines often arrive together. We built our process for those situations, with closing timelines that fit yours and no pressure to decide before you are ready.
Alek
Sell your damaged house as-is for cash
If you would rather not repair a house while a claim drags on, we buy houses, small apartment buildings and land directly from owners, in any condition, with a focus on New Jersey, Texas, Florida and Tennessee. You get a clear cash offer, no commissions or agent fees, and a closing date that works for you. Tell us about the damage and the claim, and see how selling as-is for cash works or go straight to our home buying page.
If the property also has code violations or a title problem, we can look at those together with the damage. See our guides on code violations in New Jersey and clouded title in New Jersey.
FAQ
Can I sell my house if the insurance claim is still open?
Yes. The claim belongs to you as the policyholder, and selling the house does not automatically end it. Put the claim terms in the purchase contract so nobody argues about the money later.
Does the buyer get my insurance payout?
Only if the contract assigns it and your policy and state law allow assignment. If the contract says nothing, the right to the claim generally stays with you as the seller. Ask your attorney to confirm the rule in your state.
Do I have to tell buyers about the claim?
In most cases, yes. Known damage and unrepaired conditions generally have to be disclosed, and some state forms ask about claims directly. New Jersey and Texas both require a written disclosure before the buyer is bound.
What happens if my lender is on the claim check?
The servicer usually must endorse the check, and it may hold the funds and release them in stages. At a sale, the payoff and any held claim money are normally sorted out through the title company or closing attorney.
Is the insurance payout taxable when I sell?
Payouts are generally treated as reimbursement, not income, but a payout larger than your property's adjusted basis can create a taxable gain. Check with a tax professional before you close.
Sources
- Sell Home with Open Insurance Claim in Florida, The Farber Law Firm
- If I sell my house with fire damage, will my claim still be paid out? United Policyholders
- Florida 2024 Bill 1191 text
- Understanding Our Claims Process (insurer guide)
- Edgewood Manor Apartment Homes v. RSUI Indemnity Co.
- How do home insurance companies pay out claims? CFPB
- Insured Loss Events, Fannie Mae
- R.I. Joint Reinsurance Ass'n v. Rosario
- Seller's Property Condition Disclosure Statement Instructions, NJ Division of Consumer Affairs
- Tex. Prop. Code Section 5.008
- Do I Have to Pay Taxes on Homeowners Insurance Payouts? MoneyGeek
- IRS Publication 547, Casualties, Disasters, and Thefts
- Common Structural Defects Inspection Guide