
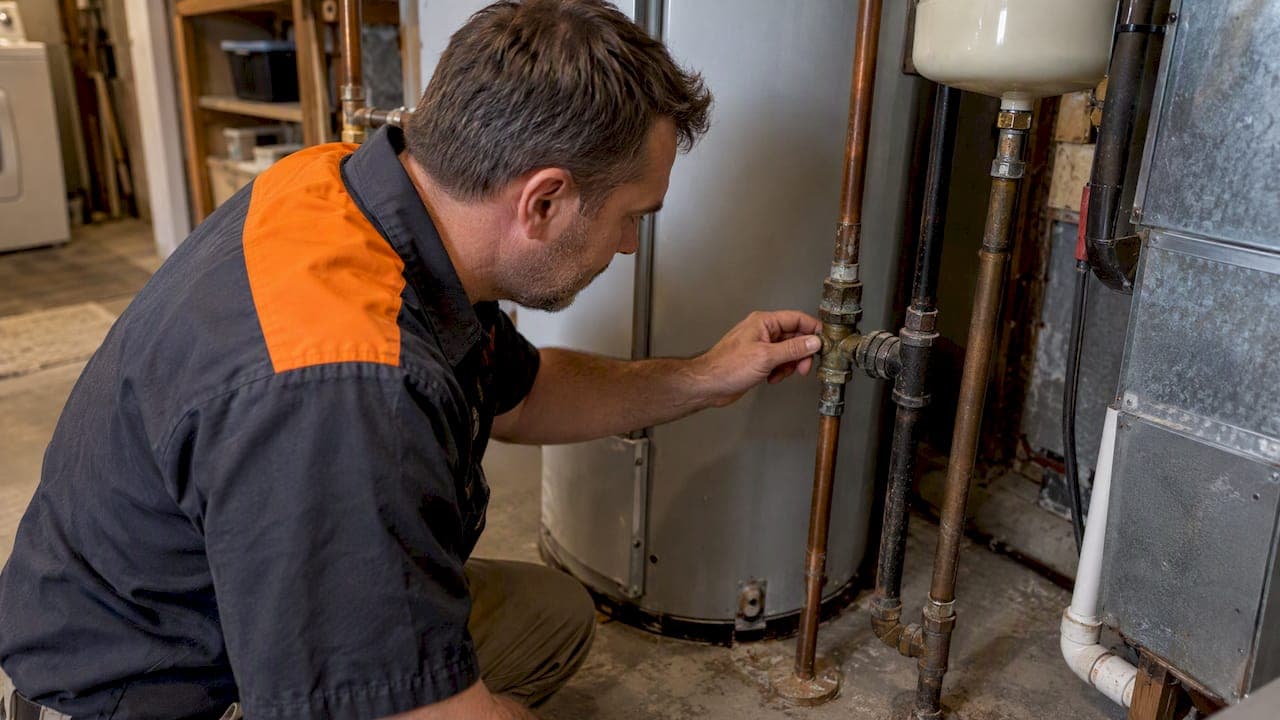
A cash purchase does not automatically remove inspection rights. Buyers can still inspect, waive inspection contingencies, or inspect for information while accepting a property as-is. Which path applies depends entirely on the contract language both sides sign, not on how the purchase is funded. Sellers, meanwhile, keep certain disclosure duties no matter what the buyer decides about inspections.
TL;DR:
- An inspection contingency commonly gives buyers 7 to 10 days to request repairs, seek a credit, or cancel; a full waiver removes those options.
- Book an inspector within a day or two of acceptance, and schedule specialty tests early because radon or septic results can take several more days.
- Federal rules require disclosure of known lead hazards and give buyers 10 days to test in most homes built before 1978, even after inspection waivers.
- Massachusetts generally bars sellers from conditioning offer acceptance on an inspection waiver, so buyers and sellers should confirm local rules before signing.
- Sellers should verify proof of funds before accepting a cash offer and document disclosures, repair requests, and price or credit changes in signed writing.
Table of Contents
- Inspection options explained: contingency, waiver, and information-only inspection
- How buyer inspections actually get scheduled in a fast cash closing
- Seller obligations and required disclosures (lead paint, radon, and state variance)
- What happens to the deal after the inspection report comes back
- Our checklist for sellers considering a cash sale
- Balancing speed and diligence in cash sales
- If you need a fast, as-is cash sale, here is how to reach us
- FAQ
- Sources
Inspection options explained: contingency, waiver, and information-only inspection
Paying cash changes how a purchase is financed, not what a buyer is legally entitled to check before closing. Three structures cover almost every cash deal.
An inspection contingency gives the buyer a window, often 7 to 10 days, to hire an inspector and respond with repair requests, a credit demand, or outright cancellation. This clause is what gives a buyer leverage after the report comes back: without it, the right to walk away or renegotiate based on findings mostly disappears.
A full waiver means the buyer gives up that contingency entirely, often to make an offer more competitive. Even so, the seller's disclosure duties do not disappear. Waiving inspection rights affects the buyer's ability to renegotiate, not the seller's legal obligation to disclose known defects.
An information-only inspection splits the difference: the buyer still hires an inspector and walks away with a full report, but the contract specifies the purchase proceeds regardless of findings. Some buyers use this structure to understand what they are getting into while still competing on price and certainty with sellers who want speed.
Key differences buyers and sellers should track before signing:
- Inspection contingency: buyer can cancel or renegotiate based on findings, within the deadline set in the contract.
- Full waiver: buyer forgoes repair requests or cancellation rights tied to inspection results.
- Information-only inspection: buyer inspects and accepts the property as-is but may still raise price concerns before signing.
- State law limits: some jurisdictions restrict how waivers can be used in an offer.
State law adds another layer. Massachusetts' Affordable Homes Act, reported by the National Association of REALTORS®, prohibits conditioning acceptance of an offer on a buyer's agreement to waive a home inspection in most residential sales. Rules like this vary by state, so sellers and buyers working across state lines should confirm local requirements with a real estate attorney rather than assume a waiver clause from one deal will hold up in another.
How buyer inspections actually get scheduled in a fast cash closing
Speed is the whole point of a cash sale, but a rushed inspection timeline still needs structure. The offer itself should spell out when the inspection must be scheduled, when the report is due, and how many days the buyer has to respond with requests or a cancellation notice.
A typical workflow looks like this:
- Negotiate inspection terms in the offer, including the contingency period (or waiver language) before signing.
- Book a licensed general inspector within a day or two of acceptance to keep the closing timeline intact.
- Order specialty tests if the property warrants them, such as radon, lead paint, septic, well water, or HVAC evaluations.
- Review the report and respond within the deadline, choosing to request repairs, ask for a credit, proceed as-is, or cancel.
- Confirm follow-up repairs or re-inspections, if any were negotiated, before the closing date.
Who pays for the inspection follows the same norms in cash deals as in financed ones. Buyers typically cover inspection costs, though sellers sometimes order a pre-listing inspection to surface issues early and keep a fast sale on track.
The Consumer Financial Protection Bureau advises scheduling an inspection as soon as possible and choosing an inspector who is accountable to the buyer, not to the seller or the deal's timeline. An inspector paid only at closing, or recommended solely by the listing side, has less incentive to flag every problem. That guidance matters just as much in a cash sale, where there is no lender-mandated inspection acting as a backstop.
Pro Tip: Book the inspector the same day your offer is accepted. Specialty follow-ups like radon or septic testing can take several more days to schedule and report back.
Seller obligations and required disclosures (lead paint, radon, and state variance)
Waiving an inspection contingency changes what the buyer can demand after the fact. It does not touch what the seller must disclose going in.
Federal law requires sellers of most homes built before 1978 to disclose any known lead-based paint hazards, provide an EPA-approved information pamphlet, and give buyers a 10-day window to test for lead paint before the contract becomes binding, under the Lead-Based Paint Disclosure Rule, Section 1018 of Title X. This rule applies whether the buyer pays cash or finances the purchase, and whether or not the buyer waives a general home inspection.

One in five buyers in a recent national sample waived inspection contingencies entirely, according to NAR's Realtors Confidence Index for September 2025, underscoring how common waivers have become in competitive markets, and why disclosure obligations matter even more when buyers skip a formal inspection.
Radon is a separate concern the EPA addresses directly for home sales. Its buyer and seller guidance recommends testing the lowest level of the home that could be regularly used and suggests remediation at or above 4 pCi/L. Sellers are advised to test before listing when possible and share results with buyers upfront.
A short checklist of what sellers should have ready regardless of how inspections are handled:
- Lead-based paint disclosure and pamphlet, for homes built before 1978.
- Any existing radon, septic, or well test results.
- Known material defect disclosures required by state law.
- Prior repair records or contractor invoices for major systems.
Local rules add more variables. Septic system age, well water quality, and flood zone designation each carry their own disclosure or inspection norms in many states, which is one reason sellers dealing with flood-prone property often lean on documentation specific to flood history when marketing to cash buyers. A local real estate attorney can confirm which disclosures apply to a specific property and state.
What happens to the deal after the inspection report comes back
Once the report lands, both sides generally land in one of four outcomes: the buyer requests repairs, asks for a credit or price reduction, accepts the property as-is, or cancels if the contract allows it.
- Repair requests work best for safety issues or major system failures the seller can fix quickly without delaying closing.
- Credits or price reductions preserve the closing date while compensating the buyer for issues the seller would rather not fix directly.
- Accepting as-is is common when the buyer already knew the property's condition going in, particularly under an information-only inspection.
- Cancellation remains available only when the contract's inspection contingency language allows it within the stated deadline.
Sellers weighing these options should think in terms of timing, not just dollars. A $3,000 credit that keeps a 10-day closing intact is often worth more than a repair negotiation that pushes the date back two weeks. Legal analysis of all-cash and waived-inspection deals notes that speed and reduced financing risk do not eliminate a seller's disclosure exposure, and documentation becomes the seller's main protection if a dispute surfaces after closing.
That means written responses to every repair request, signed addenda for any price or credit change, and verified proof of funds before accepting a cash offer at all, a step covered in more detail in guidance on verifying proof of funds before closing. Sellers who market a property with vague or overly favorable condition claims, especially when a buyer has waived inspection, carry more legal risk if problems surface later. Keeping marketing language factual and backed by documentation protects both sides.
Our checklist for sellers considering a cash sale
Some companies buy houses, small apartment buildings, and land directly from owners dealing with foreclosure, inherited property, problem tenants, vacant homes, or repairs they would rather not take on. Sellers in these situations often choose a direct cash sale because it skips the repair negotiations and financing delays that slow a traditional listing.
Before reaching out, it helps to have a few things ready:
- Any existing disclosures, including lead paint or radon results if available.
- Title documents and proof of ownership.
- Recent utility bills or repair records, if the property needs work.
- Any prior inspection reports from a previous sale attempt.
| What to verify | Why it matters |
|---|---|
| Proof of funds | Confirms the buyer can actually close in cash |
| Title company arrangement | Protects against ownership or lien disputes |
| Written offer terms | Avoids verbal agreements that can change later |
Checking a buyer's proof of funds and title company coordination before signing anything protects sellers from the kind of last-minute surprises that derail even simple cash deals.
Balancing speed and diligence in cash sales
Sellers usually come to a cash sale because something in their situation demands speed: a foreclosure deadline, an inherited property nobody wants to manage, or a tenant situation that has gone on too long. Speed is a legitimate priority, but it should not come at the cost of basic verification.
The most common mistakes we see are sellers skipping proof-of-funds checks or failing to keep a paper trail of disclosures and repair conversations. Both are easy to fix: ask for documentation before signing anything, and keep every exchange in writing.
If time allows, a pre-listing inspection can strengthen a seller's position even in a cash deal. If it does not, gathering disclosure documents and contacting a buyer with a transparent, documented process is usually the faster and safer route.
— Alek
If you need a fast, as-is cash sale, here is how to reach us
Some buyers purchase properties as-is, in cash, with no commissions or agent fees, including those needing repairs, carrying problem tenants, being vacant, or coming through probate. Our Cash Offer Program is built specifically for sellers facing foreclosure deadlines who need a closing timeline that moves faster than a traditional sale.
To get a cash offer moving quickly, it helps to have on hand:
- Proof of ownership or title documents.
- Any existing disclosures or inspection reports.
- Recent repair records or contractor estimates, if applicable.
- Mortgage payoff information, if the property carries a loan.
These buyers often provide clear, upfront offers explained in plain numbers, flexible closing dates built around the seller's situation, and direct access to decision-makers rather than a call center. Visit our how our process works page for a walkthrough of the steps, or get a cash offer today to see what your property could bring without listing it, repairing it, or waiting on a buyer's financing to fall through.
FAQ
What is the biggest red flag in a home inspection?
Major structural issues, roof failure, or active water intrusion typically concern buyers and inspectors most, since they are expensive to fix and often signal deeper problems. A roof-specific checklist can help buyers and sellers spot early warning signs before a full inspection even happens.
What should sellers expect from a home inspection?
Sellers should expect an inspector to spend a few hours examining the home's major systems, structure, and safety features, then deliver a written report to the buyer. In an as-is cash sale, the seller is generally not expected to make repairs based on that report unless the contract says otherwise.
Does someone need to be present for a home inspection?
The seller does not need to be present, and many agents recommend sellers leave so the buyer and inspector can move through the home freely. The buyer or their representative typically does attend to ask questions directly.
Do cash buyers still get inspections?
Yes. Paying cash removes a lender's inspection requirement, but buyers can still choose an inspection contingency, an information-only inspection, or a full waiver depending on how they structure their offer. The CFPB recommends scheduling an inspection promptly regardless of financing method.
Who typically pays for the home inspection?
Buyers typically cover the cost of their own inspection, according to the National Association of REALTORS® consumer guide. Sellers sometimes order a separate pre-listing inspection at their own cost to identify issues before marketing the property.
Sources
- Schedule a home inspection | Consumer Financial Protection Bureau
- Lead-Based Paint Disclosure Rule (Section 1018 of Title X) | US EPA
- Consumer Guide: Home Inspections | National Association of REALTORS®
- All-cash sales and waived inspections: Key legal risks for seller brokers in a competitive real estate market | Saiber LLP