
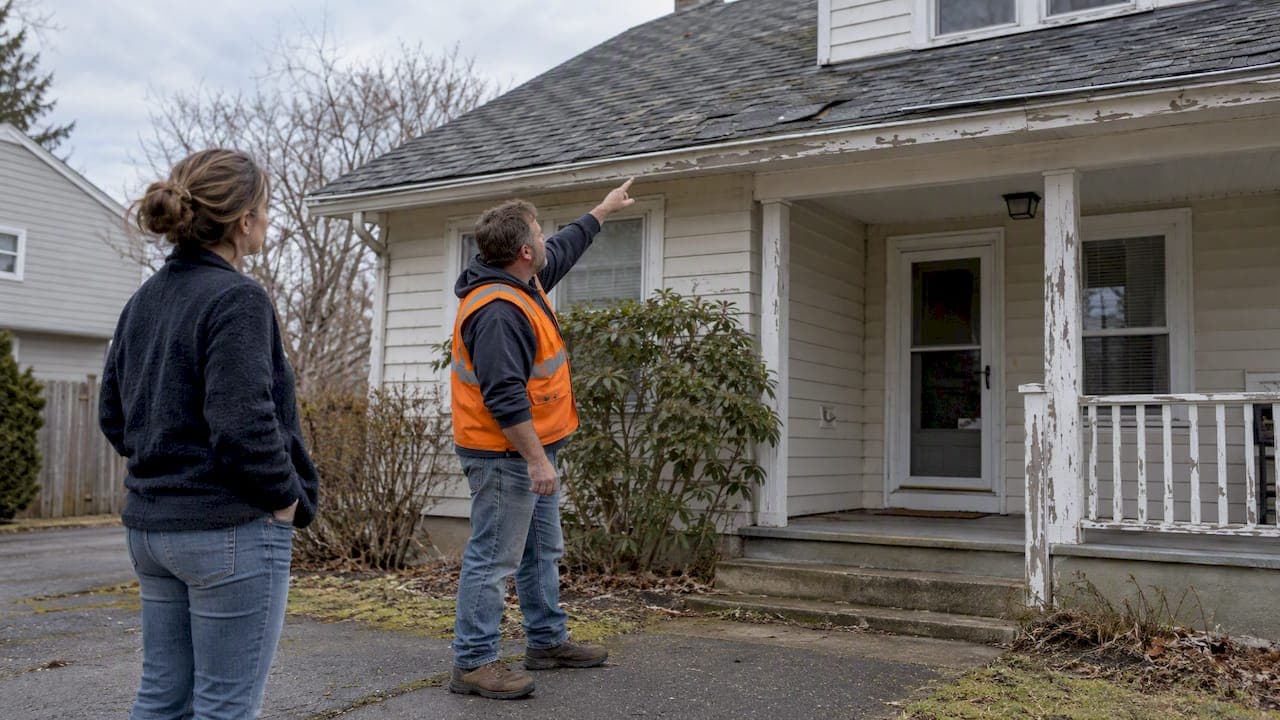
Most as-is sales close below retail price, with the gap driven by repair scope, buyer type, and how fast you need to sell. The quickest reliable way to estimate your own number is to start with an automated valuation like a Zestimate, verify it against three to six recent local comps, and subtract one real contractor estimate for major repairs. A formal appraisal or your county's listing comps won't match what a cash investor offers, because those tools answer different questions.
TL;DR:
- Repair costs significantly impact the as-is value, with structural issues reducing the price more than cosmetic upgrades.
- A reliable estimate combines an automated valuation, recent local comparables, and a contractor’s repair quote, then adjusts for buyer type and urgency.
- Small cosmetic fixes can reduce the discount, while extensive repairs or urgent deadlines tend to widen the price gap below market value.
- Appraisals often do not match investor offers because they focus on collateral security, not real market value, especially for distressed properties.
- Legal disclosure obligations still apply in as-is sales, regardless of the property being sold "as-is," and a low appraisal can prevent financed deals.
Table of Contents
- What determines an as-is home value
- How to estimate your as-is home value step by step
- Typical discounts and what moves them
- Appraisals, AVMs, and disclosure: U.S. cautions every as-is seller needs
- When selling as-is makes sense (decision checklist and short example)
- What experienced buyers actually look for in an as-is offer
- If you want a cash offer: how we evaluate as-is properties
- FAQ
- Sources
What determines an as-is home value
An as-is price reflects what a buyer will pay for your house the way it sits today, not what it could be worth after fixes. Several factors push that number up or down, and understanding them helps you read any estimate with the right skepticism.
Structural problems (foundation cracks, roof failure, outdated electrical) cost far more to price in than cosmetic ones (paint, carpet, dated fixtures), because they scare off financed buyers and often require specialized contractors. Local comparable sales set the ceiling: a strong seller's market narrows the as-is discount, while a slow market widens it. The buyer pool matters just as much as the house. Cash investors price in renovation costs and a margin for risk and time, while owner-occupants using a mortgage are constrained by lender rules that can block financing on homes with serious defects.
- Condition: structural issues cut value more than cosmetic ones, often by a wide margin.
- Comps and market strength: recent nearby sales set the realistic ceiling for any offer.
- Buyer type: cash investors and financed buyers price risk differently.
- Financing rules: lenders can disqualify homes that fail minimum property standards.
- Timing: a seller under pressure has less room to negotiate up.
How to estimate your as-is home value step by step
You don't need a license to get a reasonably accurate number. Four steps, done in order, get you close enough to negotiate with confidence.
- Run an automated valuation model. A Zestimate or similar AVM gives a fast baseline pulled from public records and recent sales, but it can't see your roof leak or your foundation crack, so treat it as a starting point, not a verdict.
- Pull three to six recent comps and adjust them. Look at homes sold in the last three to six months within a mile, then add or subtract value for differences in size, age, and visible condition.
- Get one real contractor estimate. A single walkthrough quote for the biggest repair items (roof, HVAC, foundation) beats guessing from online repair-cost charts.
- Combine the numbers. Take your adjusted comp value, subtract the contractor estimate, then apply a discount range based on buyer type and urgency.
Say your adjusted comps put the home at $300,000 in good condition, and your contractor estimate for needed repairs comes to $40,000. That leaves $260,000 before any as-is discount, which a cash buyer will further adjust downward for the risk and holding time involved in those repairs.
Pro Tip: Ask your contractor to itemize the estimate by system (roof, electrical, plumbing) so you can defend each deduction if a buyer disputes your number.

Typical discounts and what moves them
An as-is sale usually closes below what the same home would fetch move-in ready, and the size of that gap depends heavily on what's wrong with the house. A home needing only cosmetic work (paint, flooring, landscaping) tends to see a smaller discount, often in the single digits to low teens as a percentage of retail value.
- Cosmetic-only repairs tend to produce the smallest as-is discount.
- Major mechanical or structural repairs widen the gap substantially.
- An urgent sale timeline (foreclosure, relocation, probate deadline) shrinks your negotiating room.
- Local demand can offset some of the discount in a tight inventory market.
Ramsey Solutions notes that small, inexpensive fixes like cleaning and fresh paint can widen your buyer pool enough to shrink the as-is discount, so a modest cosmetic investment sometimes pays for itself before you even list.
Appraisals, AVMs, and disclosure: U.S. cautions every as-is seller needs
Appraisals and AVMs answer different questions than a cash offer does, and conflating them leads to unrealistic expectations. A documented study on home purchase appraisals found that a large share of appraisals land exactly at the contract price, and appraisals can skew upward near loan-to-value thresholds, meaning they often protect the lender's collateral position rather than reflect independent market value. That's one reason an appraisal rarely matches what an investor will offer for a distressed property.
HUD's own guidance on HUD Homes is instructive here: HUD sells these properties as-is and does not pay for repairs, pricing them off an appraised as-is value and urging buyers to get independent inspections before closing. Private as-is sales work similarly in spirit, though investor pricing also bakes in time and resale risk that a government listing doesn't.
Selling as-is never erases your legal disclosure duties. Chase's guidance on as-is sales is clear that sellers must still disclose known material defects under state law, and skipping that step can expose you to a lawsuit after closing.
- Appraisals protect lenders; they don't set your cash-offer price.
- HUD's as-is model prices off appraised value and skips repairs entirely.
- State disclosure laws still apply, "as-is" language or not.
- A low appraisal can derail a financed buyer's deal even after you've agreed on a price.
For more on how automated tools compare to formal appraisals, this breakdown of Zestimate versus appraisal accuracy is a useful read before you lean too hard on either number. You can also read our guide to what an as-is home sale actually involves for more on disclosure expectations.
When selling as-is makes sense (decision checklist and short example)
Selling as-is makes the most sense when repair costs eat too far into your proceeds, or when you simply don't have the time, cash, or appetite to manage contractors.
- Check your urgency. Foreclosure, a job relocation, or an inherited property you don't want to manage all favor a fast as-is sale.
- Run the repair ROI. Compare what repairs cost against how much value they actually add; not every fix pays for itself.
- Read the market. In a tight seller's market, listing after light cosmetic work might net more than going as-is.
- Factor in legal or tenant complications. Problem tenants, liens, or code violations often make a traditional listing harder to pull off.
Say repairs would cost $40,000 and only add $35,000 in resale value. Skipping them and selling as-is nets you more than spending money you won't fully recover. Our comparison of as-is sales versus repairs walks through that math in more detail, and sellers weighing a middle path can also look at limited cosmetic fixes, seller credits toward closing costs, or a straightforward cash-buyer route instead.
Pro Tip: Before rejecting any offer, calculate your net proceeds after repairs, carrying costs, and agent commissions, then compare that single number to the cash offer on the table.
What experienced buyers actually look for in an as-is offer
We work with property owners selling houses, land, and small apartment buildings who are dealing with difficult property situations or repairs they can't afford to tackle. What we've consistently seen is that sellers underestimate how much urgency and clean title matter to a cash offer, often more than the condition of the house itself. A property with a straightforward title and a motivated timeline frequently gets a stronger offer than a pristine house tangled in liens or probate delays.
— Alek
If you want a cash offer: how we evaluate as-is properties
We look at urgency and title status before we even calculate repair costs, because a clean, fast close is worth more to us than a house that merely looks good. Our process is simple: you request a quote, we review the property, we send a clear cash offer, and you pick a closing timeline that fits your situation.
- Basic property facts: address, square footage, and known major issues.
- Title status: liens, probate, or tenant situations we should know about upfront.
- Your timeline: whether you need to close in days or have more flexibility.
We buy properties nationwide and encourage you to compare offers before making a decision. If a fast, no-repair sale fits your situation, you can get a cash offer today and see where it lands against your other options.
FAQ
Should I sell my home as is?
Selling as-is makes sense when repair costs would outweigh the value they add, or when you need a fast, predictable close more than top dollar. It's less ideal when light cosmetic work could meaningfully widen your buyer pool and shrink the discount, as Ramsey Solutions notes.
What salary do I need to afford a $400,000 house?
Required income depends on your down payment, interest rate, debt, and local property taxes, so there's no single number that applies everywhere. A lender or mortgage calculator using your specific rate and debt load will give a more accurate figure than any general rule of thumb.
Will the U.S. housing market crash in 2026?
Current forecasts point to modest price growth and stable sales rather than a crash, according to Fannie Mae's 2026 housing outlook. That means sellers shouldn't count on a sudden market swing to close an as-is price gap quickly.
Is it better to buy or rent a home?
The better choice depends on how long you plan to stay in an area, local rent-to-price ratios, and your financial flexibility, so it varies by household and market. Sellers weighing a sale timeline should focus on their own repair and disclosure obligations rather than the broader buy-versus-rent debate.
How accurate is a Zestimate for pricing an as-is home?
A Zestimate is a useful starting point but doesn't account for a home's actual condition, so it should always be checked against recent local comps and, ideally, a contractor's repair estimate. Treat it as a baseline rather than a final number, especially for homes with significant repair needs.
Sources
- Information losses in home purchase appraisals (Calem et al.)
- Selling a House As Is - Ramsey Solutions
- Hud
- Selling a House 'As Is': What to Know (Chase)
- Fannie Mae 2026 housing forecast (RealtyWire summary)