
You can usually stop a Tennessee foreclosure by contacting your loan servicer today and submitting a complete loss-mitigation application under 12 C.F.R. § 1024.41, or by reinstating your loan if your deed of trust allows it. If you're already close to a sale date, a HUD-approved housing counselor or the Tennessee Housing Development Agency can help you move fast. A Chapter 13 bankruptcy filing triggers an automatic stay that halts the sale immediately.
First 24 hours:
- Call the servicer number on your mortgage statement and ask about loss mitigation.
- Pull your loan paperwork and screenshot any missed-payment notices.
- Call a HUD-approved counselor at 800-569-4287 or the Homeowners HOPE Hotline at 888-995-HOPE.
- Contact THDA if you're a Tennessee resident needing local referrals.
Pro Tip: Bankruptcy's automatic stay under 11 U.S.C. § 362 stops a sale cold, but it's a legal maneuver with lasting credit consequences, not a first move.
Key Takeaways
Stopping a Tennessee foreclosure comes down to acting before the trustee's sale is published, using free HUD and THDA resources, and choosing the legal or sale option that matches your remaining timeline.
| Point | Details |
|---|---|
| Call your servicer first | Request loss mitigation immediately; a complete application before publication is your strongest ordinary defense. |
| Use free counseling | HUD-approved counselors (800-569-4287) and THDA negotiate with servicers at no cost to you. |
| Know your legal tools | Reinstatement, forbearance, modification, short sale, and Chapter 13's automatic stay each fit different timelines. |
| Watch for scams | Legitimate help is free; never pay upfront fees or transfer your deed to a stranger. |
| Consider a cash sale | Exitvest buys Tennessee homes as-is and can close before an auction date when timing is tight. |
Table of Contents
- How Tennessee Foreclosures Usually Proceed and Why Timing Is Critical
- Options That Can Stop or Delay a Foreclosure in Tennessee
- Free Tennessee Resources and Hotlines to Call First
- Foreclosure Rescue Scams to Watch For
- When Selling Your House for Cash Is the Right Move
- Your 24 to 72 Hour Checklist
- How ExitVest Can Help Stop Foreclosure by Buying Your Tennessee Home
- Frequently Asked Questions
- Sources
How Tennessee Foreclosures Usually Proceed and Why Timing Is Critical
Tennessee is a fast, nonjudicial foreclosure state. Lenders foreclose using the power-of-sale clause in your deed of trust rather than going through court, which is exactly why the clock moves quicker here than in judicial states.
A typical sequence looks like this:
- Federal rules give most homeowners a pre-foreclosure window after the first missed payment before a servicer can even start the process.
- Once that window closes, the servicer sends formal notice by certified or registered mail.
- Tennessee law requires the first published notice at least 20 days before the sale date, with recent changes also requiring online posting.
- The sale happens in the county where the property sits, often on the courthouse steps.
Reinstatement and redemption rights are usually spelled out in your deed of trust, not guaranteed by state law. Many standard Tennessee deeds waive the post-sale statutory redemption period, so check your paperwork now rather than after the sale. The strongest ordinary move is getting a complete § 1024.41 application to your servicer before that publication clock starts running, because once publication begins, your options compress fast.
Options That Can Stop or Delay a Foreclosure in Tennessee
Several tools exist, and which one fits depends almost entirely on how much time you have left before the sale date.
Reinstatement. Pay the full past-due balance, fees, and costs in one lump sum to bring the loan current. Your deed of trust or promissory note dictates whether you're allowed to reinstate and what the payoff calculation includes, so get a written reinstatement quote from your servicer rather than estimating.
Repayment plan or forbearance. These short-term fixes spread missed payments over several months or pause them temporarily. Servicers typically want proof of a temporary hardship (a job loss, medical bill, or disaster) plus recent pay stubs and bank statements.
Loan modification. A permanent change to your loan terms, usually a lower rate or extended term. This runs through the same § 1024.41 process, and CFPB guidance notes servicers must review a complete application before proceeding with a scheduled sale, which is why completeness and timing both matter.
Short sale or deed in lieu of foreclosure. Selling the home for less than what's owed, or handing the deed back to the lender, both avoid a foreclosure on your record and can preserve whatever equity remains instead of losing it at auction.
Bankruptcy and the automatic stay. Filing Chapter 13 triggers an automatic stay that stops the sale the moment you file, even if it's scheduled for the next morning. It buys time to catch up through a repayment plan, but it stays on your credit report for years and needs a bankruptcy attorney's guidance to use correctly.
Pro Tip: Once the trustee publishes the first notice of sale, your window for a modification or repayment plan narrows sharply. If you're past publication, bankruptcy or a fast cash sale become your realistic options.
Free Tennessee Resources and Hotlines to Call First
You don't need to pay anyone for foreclosure help. These are the legitimate, no-cost starting points:
- THDA coordinates HUD-certified counseling statewide and can connect you with Volunteer Mortgage Loan Servicing (VMLS) where applicable for Tennessee-backed loans.
- HUD-approved housing counselors (800-569-4287) will review your finances for free and can negotiate directly with your servicer on your behalf.
- The Homeowners HOPE Hotline (888-995-HOPE) and HOPE NOW, an industry coalition, both connect homeowners to loss-mitigation resources at no charge.
- The CFPB's homeowner assistance fund guidance explains how to check for state or federal relief funds you may qualify for.
Call these in this order: your servicer, then a HUD counselor or THDA, then explore HAF funds if you need direct financial assistance.
Foreclosure Rescue Scams to Watch For
Anyone asking for money up front to "guarantee" they'll stop your foreclosure is running a scam. So is anyone who tells you to stop talking to your servicer or asks you to sign over your deed to a stranger's company. The FTC warns that these tactics show up constantly around distressed homeowners, and both THDA and HUD repeat the same warning: real counseling is always free.
Beware of anyone who charges a fee for help you can get free from a HUD-certified counselor, or who asks you to redirect your mortgage payments to them instead of your servicer.
If something feels off, stop responding, save every email and text as evidence, and report it to HUD or your state's consumer protection office.
When Selling Your House for Cash Is the Right Move
If you're past publication, can't qualify for a modification, or you're staring down a pile of repairs and liens you can't afford to fix, a fast cash sale often makes more sense than fighting a losing timeline. The process is simple: get an offer, accept it, and close on a schedule that fits your situation, sometimes fast enough to close before the auction date even arrives.
This route tends to fit best when:
- The sale date is close and a modification won't process in time.
- The property needs repairs you can't finance.
- You inherited the home and don't want to manage it through a legal deadline.
- Liens or code violations complicate a traditional sale.
ExitVest buys Tennessee properties as-is, including homes in active foreclosure, and can close on a timeline built around your sale date rather than a buyer's mortgage approval.
Your 24 to 72 Hour Checklist
Gather these documents now:
- Mortgage note and deed of trust.
- Payment history and any payoff quote from your servicer.
- Recent letters or notices from your lender.
- Homeowner's insurance policy and property tax records.
When you call your servicer, ask directly: "I want to apply for loss mitigation. What's your complete application checklist, and what's my deadline before publication?" Ask a counselor the same question, and keep a written log of every call, name, and date.
Pro Tip: Upload everything to a cloud folder the same day you receive it, and screenshot the delivery confirmation on anything you email your servicer. That timestamp matters if a dispute comes up later.
A Tennessee Property Buyer's Take
Homeowners rarely wait too long on purpose. They wait because no one gives them a clear next step. A fast, as-is cash sale exists for exactly the moment when the legal options have run out of runway.
How ExitVest Can Help Stop Foreclosure by Buying Your Tennessee Home
If you've called your servicer, talked to a counselor, and the math still doesn't work, selling for cash gets you out from under the deadline instead of racing it. Exitvest buys Tennessee houses, land, and small apartment buildings as-is, with no agent commissions and no repair requests, and structures the closing timeline around your specific sale date.
The process starts with a quick conversation about your situation, followed by a fair cash offer, usually within a day or two. You choose the closing date, whether that's fast enough to beat an upcoming auction or a few weeks out if you need more breathing room. There's no showings, no financing contingencies, and no waiting on a buyer's mortgage approval to fall through. Request a cash offer on your property and find out whether closing before your sale date is realistic for your timeline.
Frequently Asked Questions
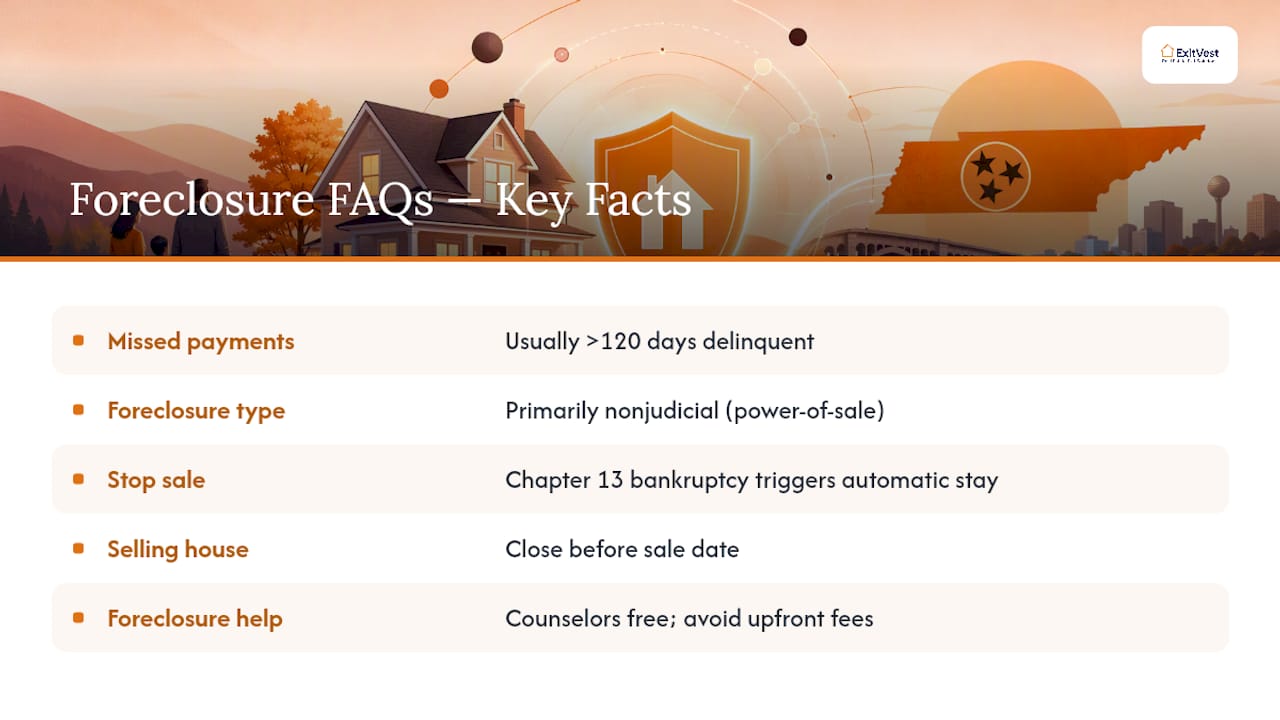
How many missed payments before foreclosure starts in Tennessee? Federal rules generally require the loan to be more than 120 days delinquent before a servicer can begin the foreclosure process, though your specific deed of trust and servicer policy may vary.
Is Tennessee a judicial or nonjudicial foreclosure state? Tennessee primarily uses nonjudicial foreclosure through the power-of-sale clause in a deed of trust, which is why the timeline from notice to sale moves faster than in court-supervised states.
Can I stop a foreclosure sale at the last minute? Filing Chapter 13 bankruptcy triggers an automatic stay that stops a scheduled sale immediately, though it's a legal decision best made with a bankruptcy attorney given the long-term credit impact.
Does selling my house stop the foreclosure? Yes, if you close before the sale date. A short sale or a cash sale to a buyer like Exitvest can settle the debt and avoid the foreclosure appearing on your credit history.
Is foreclosure help really free in Tennessee? Yes. THDA and HUD-approved counselors never charge for their services, and any company demanding upfront fees to "stop" your foreclosure is a red flag worth reporting.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Foreclosure Prevention (Tennessee Housing Development Agency)
- Summary of Tennessee's foreclosure laws (Nolo)
- How to avoid foreclosure (CFPB educational PDF)